Your home. Your next chapter. Know your options.
Explore how your home equity could support the retirement you have planned—with clear answers from Glen Smart and Robin Loomis.
A conversation. Clear answers. No pressure.
Local Guidance
We live and work here—and understand the communities we serve.
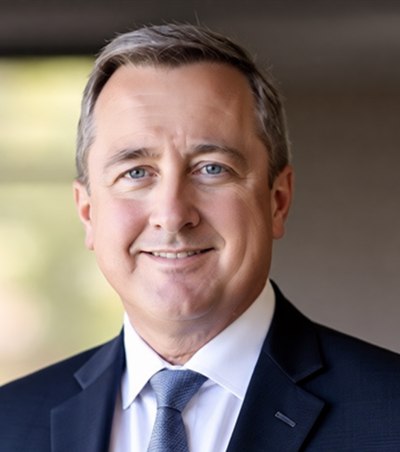
Glen Smart, CRMP
NMLS #208695
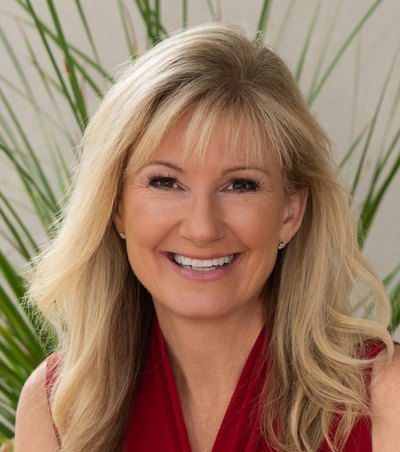
Robin Loomis, CRMP
NMLS #461651
Backed by NOVA Home Loans
A trusted lender with resources to help you move forward confidently.
Smart Retirement Equity Explorer
Start with your numbers—
not a sales pitch.
See a customized, educational estimate before sharing contact information. A licensed specialist can then prepare a personalized loan estimate.
- Understand the equity you have built
- See which retirement pathways merit a closer look
- Bring better questions to your conversation
Robin can prepare your estimate
Get a personalized estimate for your home in a short call. No obligation.
Call Robin 520-677-3177Clear from the beginning
A thoughtful process, one conversation at a time.
-
1
Explore
Use the Equity Explorer and educational resources privately, at your own pace.
-
2
Understand
Review responsibilities, costs, alternatives and potential strategies with Robin.
-
3
Decide
If a reverse mortgage fits, move forward with formal disclosures and independent HUD-approved counseling.
More than a number
See the trade-offs—not just the potential proceeds.
A useful retirement-equity conversation should examine today’s cash flow, future loan balance, remaining equity and the responsibilities of staying in the home.
Illustrative categories only. Your licensed specialist will use current terms and assumptions.
Taking a closer look
Keeping a low first-mortgage rate? Compare a second.
A reverse second is an alternative to a traditional home equity line of credit (HELOC), with no required monthly mortgage payments on the second loan. Your first mortgage payment continues, and you must still pay property taxes and homeowners insurance and maintain the home. See how it stacks up.
| Feature | Reverse Second | HELOC1 |
|---|---|---|
| Interest rate type | Fixed or adjustable, by program | Variable |
| Loan type | Varies by program | Line of credit |
| Minimum credit score | Varies by program | 680 |
| Monthly mortgage payments required | No required monthly mortgage payments on this second loan. You must still make your first mortgage payment, pay property taxes and homeowners insurance, and maintain the home. You can make a payment at any time without penalty to preserve equity | Yes. Interest only for 10 years, then fully amortizing over 20 years |
| Minimum age | Yes. 55, 60, or 62 depending on your state and program | No |
| Borrower still owns home | Yes | Yes |
| Repayment | Due when the borrower moves, leaves the property, fails to pay taxes or insurance or violates the terms of the loan | 30 years. Interest only for 10 years, then fully amortizing over 20 years |
1 This is an educational example of one HELOC. Requirements, payment and other terms may vary between lenders. These materials are not from HUD or FHA and were not approved by HUD or a government agency. Proprietary reverse mortgages and reverse second loans are not affiliated with the Home Equity Conversion Mortgage (HECM) program and are only available in certain states. Other conditions and restrictions may apply. Rates and available loan programs are subject to change without notice.
The Smart Team
Experience you can talk to.
Reverse mortgages are personal. Glen and Robin bring decades of mortgage experience—and a shared commitment to clear, pressure-free guidance.
Reverse Mortgage Specialist
Robin Loomis, CRMP
520-677-3177Ask for Robin, and the assistant who answers will connect you.
For professionals
A clear resource for the clients you advise.
CPAs, attorneys, financial planners, realtors and title and escrow professionals can send clients to Robin for clear, pressure-free education. For clients who are right-sizing or stepping up, HECM for Purchase may be worth a conversation.
Your clients are always free to choose any lender or advisor.
Common questions
Start with the questions that matter.
You retain title to your home, subject to the loan. You must continue meeting the loan obligations, including paying property taxes and homeowners insurance and maintaining the property.
HECMs have no required monthly mortgage payments. You must still pay property taxes and homeowners insurance, maintain the home and meet the loan terms. The loan balance grows over time.
The amount depends on several factors, including the age of the youngest eligible borrower, home value, existing liens, current rates and the selected program. Robin can prepare a personalized estimate.
When the loan becomes due, borrowers or heirs generally may repay the balance, refinance if eligible, sell the property, or explore other available options with the servicer.
For an FHA-insured Home Equity Conversion Mortgage, independent counseling with a HUD-approved counselor is required before the loan can proceed. You can search HUD’s list by ZIP code below.
Independent counseling
Find a HUD-approved counselor.
Before an FHA-insured HECM can move forward, you meet with an independent HUD-approved counselor. Counselors don’t work for any lender, and many meet by phone or video.
Prefer to search on HUD’s website?
Agencies are listed by distance from HUD’s housing counselor data. The Smart Team and NOVA Home Loans don’t recommend or endorse any agency, and you’re free to choose any HUD-approved HECM counselor.
A Brighter Tomorrow
Still Starts At Home
Local Guidance